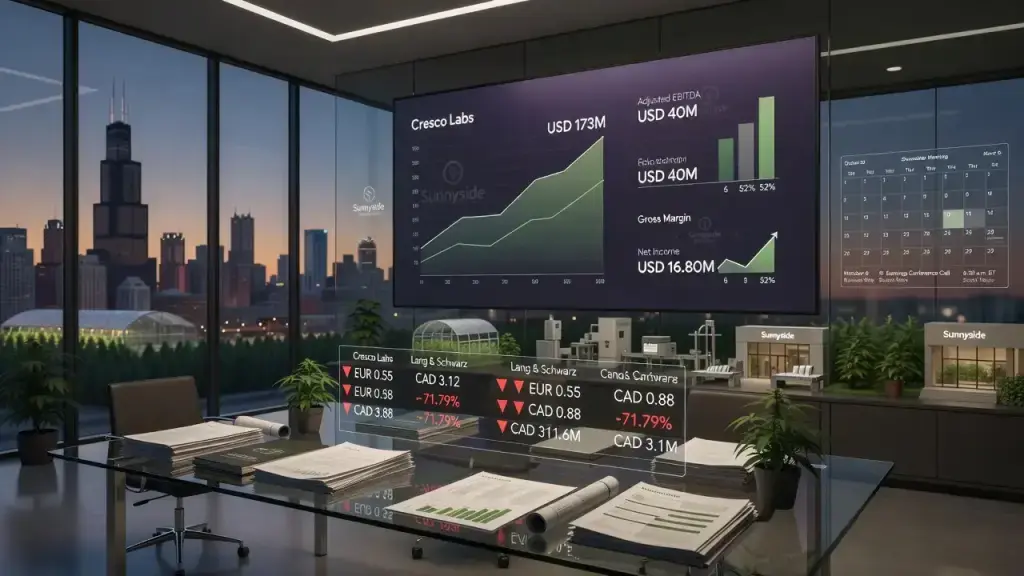
Cresco Labs will report third-quarter 2026 results on November 6, before the market opens, with a conference call scheduled for 8:30 a.m. ET, the company confirmed through Business Wire on October 15. The date gives investors a fixed checkpoint after a second quarter that showed sequential revenue growth but left the multi-state operator's shares trading at a fraction of their 52-week high.
What the Last Quarter Actually Showed
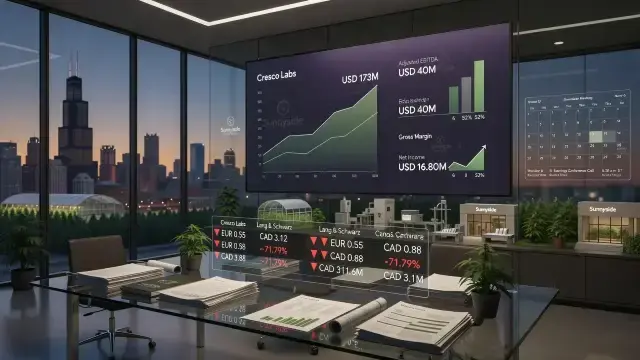
The second-quarter print, detailed by ScanX News on October 6, had some genuinely decent operating signals buried in it. Revenue climbed 15.00 percent sequentially to USD 173 million, adjusted EBITDA rose 20.00 percent to USD 40 million, and adjusted gross profit hit USD 89 million - a 52.00 percent margin. A standardized financial statement pegs revenue at USD 173.34 million with net income of USD 16.80 million for the period. That's a respectable gross margin for a vertically integrated operator juggling cultivation, processing, and retail through its Sunnyside dispensary banner across eight states. In practice, though, margin strength at the operating level doesn't automatically translate into a clean earnings picture once 280E tax treatment, interest expense, and non-cash charges work their way down the income statement.
The Valuation Gap Investors Are Watching
Here's the catch. Cresco shares traded at EUR 0.55 on Lang & Schwarz on October 15 at 10:13 p.m. CEST, with a bid of EUR 0.53 and an ask of EUR 0.56. On its Canadian listing, the stock last changed hands at CAD 0.88 the same day at 3:50 p.m. ET - a level that sits 71.79 percent below its 52-week high of CAD 3.12. Market capitalization stood at CAD 311.6 million, and the price-to-earnings ratio was negative 1.96, a figure that simply confirms what operators in this sector already know: a loss-making earnings base is still the norm for many plant-touching multi-state operators, even ones posting double-digit sequential revenue gains. The gap between improving unit economics and a battered share price is not unique to Cresco. It reflects a broader pattern across cannabis equities, where federal tax treatment under 280E, limited access to traditional banking, and capital markets that remain wary of federally illegal businesses keep valuations compressed regardless of quarterly performance.
Why the Calendar Matters for Operators and Suppliers
For wholesale partners, landlords, and brands that sell into Sunnyside stores, scheduled disclosure dates like November 6 are not just investor trivia. They're the moments when payment terms, inventory commitments, and expansion plans get reassessed. A multi-state operator's cash generation trajectory - adjusted EBITDA growth, gross margin trends, free cash flow - shapes how aggressively it can invest in new store builds, POS upgrades, or compliant packaging redesigns mandated by state regulators. Suppliers watching the November print will be looking past the headline revenue number toward cash flow from operations and any commentary on capital allocation.
A Second Dated Milestone Already on the Calendar
Cresco also has an annual and special shareholder meeting set for October 30, ahead of the earnings release. Together, the two dates give the market a short runway of concrete events rather than speculation. For a company founded in 2013 and now employing thousands across cultivation, processing, and retail operations, the combination of a governance meeting and a quarterly results call offers a clearer read on strategy than either event alone. Whether the November 6 numbers reinforce the second quarter's margin improvement - or expose cracks beneath it - will matter more to the stock than the calendar date itself.